Saving money is one of the most useful habits you can develop for a more secure financial future. Save Money Whether you earn a regular salary, work as a freelancer, run a small business, or manage household expenses, having savings can make everyday life less stressful. It gives you a financial cushion for unexpected bills, helps you prepare for important milestones, and allows you to make decisions without depending entirely on your next paycheck.
However, building savings is not always easy. Rising living costs, monthly bills, shopping expenses, and unexpected payments can leave little money at the end of the month. The good news is that you do not need a large income to begin saving. A few practical changes in the way you manage your money can help you build a consistent savings habit.
This guide explains how to save money through better budgeting, smarter spending, realistic financial goals, and simple everyday habits that can help your savings grow over time.
The “Pay Yourself First” Automation Save Money
The most common mistake is trying to save whatever is left over at the end of the month—because there is rarely anything left.
- The Fix: Treat your savings like a non-negotiable bill. On the exact day your salary hits your account, set up an automated recurring transfer directing 10%–20% straight into a separate savings or investment account.
- The Psychology: You adapt your monthly lifestyle spending around the remaining balance in your main checking account without feeling deprived.
High-Yield Capital Allocation
Leaving your emergency fund or long-term cash reserves in a standard low-interest checking account exposes your purchasing power to inflation.
- High-Yield Savings Accounts (HYSA) / Liquid Mutual Funds: Move emergency reserves (3 toBuilding real, lasting savings isn’t about extreme deprivation, skipping every small pleasure, or living on a shoestring budget. It’s about building a simple, friction-free system that protects you when life gets unpredictable—while still letting you enjoy your daily life.
Here are six high-impact strategies to help you stop overthinking personal finance and start growing your savings consistently.
1. Shift Your Mindset: Why “Willpower” Fails
If your strategy for saving money relies purely on self-control, you will eventually burn out. Every time you say “no” to a night out, a ride-share on a rainy day, or a quick food delivery, you exhaust a finite amount of mental energy. By the end of a long workweek, your willpower is drained, making it easy to make impulsive financial decisions.
Sustainable saving relies on friction, automation, and mindset shifts:
- Automate the Decision: Don’t ask yourself every month, “How much should I save this time?” Decide once, set up an automatic recurring transfer on payday, and let the system run on autopilot.
- Out of Sight, Out of Mind: Keep your primary savings account at a completely different bank than your daily spending account. If you see a high balance every time you open your main banking app to pay for groceries, your brain falsely assumes you have extra cash to blow.
- Stop Calling It “Sacrifice”: Saving money isn’t giving up your present life for a distant future; it’s buying your freedom. A solid savings balance gives you the power to handle an unexpected crisis, change careers, or take time off without taking on high-interest debt.
2. Structure Your Accounts for Zero Confusion Save Money
Lumping all your money into one standard checking account is a fast track to accidental overspending. To keep your finances organized effortlessly, separate your money into dedicated digital buckets:
                          [ Monthly Income ]
                                  │
         ┌────────────────────────┼────────────────────────┐
         ▼                        ▼                        ▼
[ Bills & Rent Account ]  [ Daily Spending ]    [ High-Yield Savings ]
 (Fixed Essentials)         (Variable Wants)     (Emergencies & Goals)
- The Bills Account: Money goes in on payday, and automatic payments for rent, utilities, loan EMIs, and insurance go out. You never touch the debit card tied to this account for personal spending.
- The Daily Spending Account: This is your guilt-free allowance for the month. Once you cover your fixed costs and auto-transfer money to your savings, whatever is left in this account is yours to spend on food, entertainment, and shopping without second-guessing yourself.
- The Emergency Reserve: Kept at a separate bank offering competitive interest rates. This is reserved strictly for genuine crises—job loss, major home repairs, or medical emergencies.
3. High-Impact Moves Save Money: Cut the Big Overhead
Cutting out a small coffee saves pocket change, but renegotiating major recurring expenses frees up substantial cash with far less ongoing effort. Focus your energy where the numbers actually matter:
Audit Your Fixed Monthly Overheads
Every six months, sit down with your bank statement and review every recurring expense:
- Subscriptions & Services: Cancel anything you haven’t used in the past 30 days. You can always resubscribe later if you genuinely miss it.
- Phone & Internet Plans: Call your service provider. Carriers frequently launch newer, cheaper plans for new customers while quietly letting existing users overpay on legacy tiers. Ask for a loyalty discount or threaten to switch.
- Insurance Premiums: Never auto-renew health, car, or home insurance without running a quick comparison on aggregator sites. Policies change annually, and switching providers can easily save you significant money every year.
Master the “48-Hour Cool-Off” Rule
Impulse buying is engineered by targeted ads and one-click checkouts. Break the cycle by imposing a mandatory 48-hour cooling-off period on any non-essential purchase over a set limit.
Add the item to your cart, close the tab, and walk away. Most of the time, the impulse fades, and you’ll realize two days later that you didn’t actually need or want the item in the first place.
4. Tackle Debt vs. Building Savings
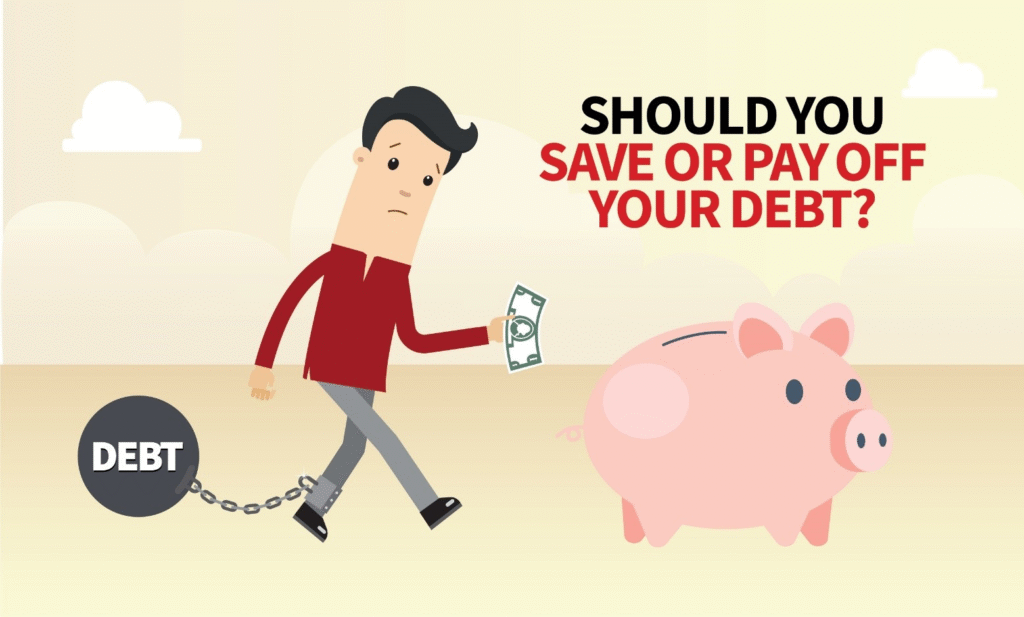
One of the most common personal finance questions is whether to pay off debt or build savings first. The right path depends on the type of debt you hold.
Is your debt high-interest? (Credit cards, personal loans > 12-15%)
 ├── YES ──► Build a mini-emergency fund first (e.g., 1 month of basic expenses).
 │           Then aggressively throw every extra dollar/rupee at the high-interest debt.
 │
 └── NO ───► (Low-interest debt like mortgages, student loans)
             Maintain regular minimum payments while simultaneously building
             a full 3-to-6 month emergency reserve.
Payoff Strategies
- The Debt Avalanche (Math-Optimized): Pay minimums on everything, then channel all extra funds into the debt with the absolute highest interest rate. This mathematically saves you the most money in interest over time.
- The Debt Snowball (Psychology-Optimized): Pay off your smallest balance first, regardless of the interest rate. Crossing a debt off your list gives you an immediate psychological victory, creating momentum to tackle the bigger balances.
5. Beat “Lifestyle Creep” When Your Earnings Rise Save Money
As your career progresses and your earnings grow, there is an almost irresistible urge to upgrade every aspect of your life—a nicer apartment, a more expensive car, costlier clothes, and frequent fine dining. This is known as lifestyle inflation, and it is the primary reason high earners can still end up living paycheck to paycheck.
To enjoy your raises without sabotaging your financial growth, follow the 50% Promotion Rule:
Every time you get a raise, bonus, or windfall, immediately redirect at least 50% of the net increase straight into your long-term savings or investments. Use the remaining 50% to upgrade your lifestyle and reward yourself.
This guarantees that your savings rate accelerates naturally alongside your income, without forcing you to live a life of artificial austerity.
6. Action Plan: A Simple 30-Day Checklist
If you aren’t sure where to begin, use the next month to establish a practical financial baseline:
- Track the Flow. Review your last 30 days of bank transactions to see where your money actually went.
- Set Up Accounts. Open a secondary high-yield savings account at a separate bank from your primary checking account.
- Automate. Schedule an automatic transfer of 5% to 10% of your income to occur the day after your paycheck lands.
- Review Fixed Bills. Cancel two unused subscriptions and call your phone/internet provider to negotiate a better rate.
Disclaimer: This guide is for educational and informational purposes only and does not constitute formal financial advice.
Frequently Asked Questions
1. How can I save money every month?
Create a monthly budget, track your expenses, reduce unnecessary spending, and transfer a fixed amount into your savings account after payday.
2. What is the best way to grow savings?
Save consistently, set clear financial goals, build an emergency fund, and choose suitable savings options based on your financial needs.
3. How much money should I save each month?
Saving around 20% of your take-home income is a common guideline, but you can start with a smaller percentage that fits your budget.
4. How can I save money on a low income?
Prioritize essential expenses, plan grocery shopping, avoid impulse purchases, and set a small, achievable savings target.
5. What is the 50/30/20 budgeting rule?
It is a budgeting method that allocates 50% of income to needs, 30% to wants, and 20% to savings and debt repayment.