Debt can make your monthly budget feel tighter than it really is. Debt Management A credit card balance, personal loan, education loan, car payment, or several smaller debts can quickly become difficult to keep track of when payments start competing with everyday expenses.
The good news is that debt management does not have to mean making extreme changes to your lifestyle. Debt Management A clear repayment plan, realistic budget, and better understanding of your interest rates can make the process much easier to handle.
Debt management is about taking control of what you owe, deciding where your money should go each month, and gradually reducing your outstanding balances. The right approach depends on your income, expenses, interest rates, repayment terms, and financial priorities.
Whether you are dealing with one large loan or several smaller balances, this guide covers practical ways to organize debt, reduce interest costs, save money, and build healthier money habits.
What Is Debt Management?
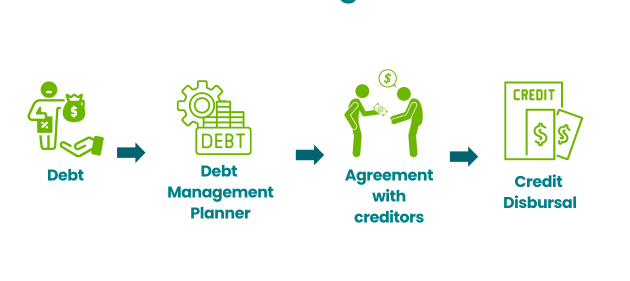
Debt management is the process of organizing and managing borrowed money so that repayments remain affordable and debt gradually decreases.
Debt Management It starts with knowing exactly what you owe. That means looking at your outstanding balances, interest rates, minimum payments, due dates, and loan terms.
Once everything is visible, you can create a repayment strategy that fits your budget.
Debt management can include:
- Creating a debt repayment budget
- Paying bills on time
- Prioritizing high-interest debt
- Reducing unnecessary expenses
- Avoiding additional borrowing
- Consolidating certain debts when appropriate
- Building an emergency fund
- Negotiating with lenders when possible
- Tracking progress regularly
The aim is not simply to make payments. Debt Management It is to create a system that helps reduce debt while keeping your overall finances manageable.
Debt Management at a Glance
| Debt Management Strategy | How It Helps | Best For |
|---|---|---|
| Create a debt list | Gives you a complete picture of what you owe | Everyone |
| Debt snowball | Builds motivation through quick wins | People who prefer visible progress |
| Debt avalanche | Focuses on high-interest balances | Saving more on interest |
| Budgeting | Creates room for debt payments | Anyone with limited cash flow |
| Expense reduction | Frees up extra money | Tight monthly budgets |
| Debt consolidation | Combines eligible debts into one payment | Multiple qualifying debts |
| Automatic payments | Helps avoid missed due dates | Busy borrowers |
| Emergency savings | Reduces reliance on new credit | Most households |
| Extra payments | Can reduce balances faster | Borrowers with spare cash |
| Professional advice | Provides personalized guidance | Complex or difficult debt situations |
Start by Knowing Exactly What You Owe
The first step toward better debt management is surprisingly simple: write everything down.
Create a list of your debts and include the important details for each one.
| Debt | Balance | Interest Rate | Minimum Payment | Due Date |
|---|---|---|---|---|
| Credit Card A | ₹XX,XXX | XX% | ₹X,XXX | XX |
| Personal Loan | ₹XX,XXX | XX% | ₹X,XXX | XX |
| Car Loan | ₹XX,XXX | XX% | ₹X,XXX | XX |
| Education Loan | ₹XX,XXX | XX% | ₹X,XXX | XX |
You can replace the placeholders with your actual numbers.Debt ManagementThis simple list can reveal which debts are costing you the most and where your repayment strategy should begin.
Build a Realistic Debt Repayment Budget
A repayment plan works better when it reflects your actual life.
Start with your monthly income and subtract essential expenses such as:
- Rent or housing costs
- Food and groceries
- Utilities
- Transportation
- Insurance
- Education expenses
- Medical and household needs
- Minimum debt payments
The money left after essential expenses can then be divided between savings, extra debt payments, and reasonable spending.
Avoid creating a budget so restrictive that you cannot maintain it. A plan you can follow consistently is more useful than an aggressive plan that lasts only a few weeks.
Choose a Debt Repayment Strategy
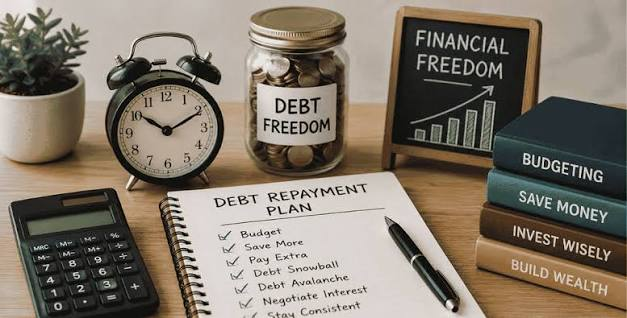
Two popular approaches are the debt snowball and debt avalanche methods.
Debt Snowball Method
With the debt snowball approach, you focus on paying off your smallest balance first while continuing minimum payments on other debts.
Once the smallest debt is cleared, the money that was going toward it can be redirected to the next balance.
The psychological benefit is straightforward: seeing a debt disappear can provide motivation to continue.
Debt Avalanche Method
The debt avalanche approach prioritizes the debt with the highest interest rate.
You continue making required payments on other debts while putting additional money toward the highest-interest balance.
Once that debt is paid, you move to the next-highest interest rate.
This approach can reduce the amount of interest paid over time, although the first debt payoff may take longer if the highest-interest balance is large.
Snowball vs. Avalanche
| Feature | Debt Snowball | Debt Avalanche |
|---|---|---|
| Main focus | Smallest balance | Highest interest rate |
| Early payoff | Often quicker | May take longer initially |
| Motivation | Strong psychological reward | Focuses on interest savings |
| Ideal for | People who like quick wins | People focused on reducing interest |
| Key requirement | Consistent payments | Consistent payments |
There is no single repayment method that works for everyone. Your income, debt structure, interest rates, and personal habits all matter.
Focus on High-Interest Debt
Interest can make debt considerably more expensive over time.
Credit card balances and other high-interest borrowing can grow quickly when balances remain unpaid. If your budget allows, directing extra money toward expensive debt can help reduce future interest costs.
Before making additional payments, check the terms of your loan. Some financial products may have specific rules or fees related to early repayment.
Make More Than the Minimum When You Can
Minimum payments help keep accounts current, but paying only the minimum can result in a longer repayment period and more interest.When you have extra money available, consider putting some of it toward your debt.
Extra money could come from:
- A bonus
- A tax refund
- Freelance income
- Selling unused items
- A temporary spending reduction
- A side income stream
- A cash gift
You do not have to put every unexpected rupee toward debt. Maintaining some savings for emergencies can also help prevent new borrowing when an unexpected expense appears.
Cut Expenses Without Making Life Miserable
Reducing spending does not mean removing every enjoyable activity from your budget.
Instead, look for expenses that are easy to adjust.
For example:
- Review streaming subscriptions.
- Compare phone and internet plans.
- Cook at home more often.
- Reduce impulse shopping.
- Plan grocery purchases.
- Use loyalty or cashback programs responsibly.
- Compare insurance or service costs at renewal.
- Set a monthly entertainment limit.
Small monthly savings can become meaningful when they are consistently redirected toward debt.
Avoid Adding New Debt
Paying off existing debt becomes much harder when new balances continue appearing.
Before using a credit card or taking another loan, ask yourself whether the purchase is necessary, whether it fits your current budget, and whether the repayment will interfere with your existing plan.
For recurring expenses, building them into your monthly budget can reduce the need to rely on credit.
Build an Emergency Fund
Debt repayment and emergency savings can work together.
Without any emergency savings, an unexpected repair, medical bill, job interruption, or urgent household expense could force you to borrow again.
Even a small emergency fund can provide a financial buffer.
You can start with a manageable amount and gradually increase it as your financial situation improves.
The right emergency-fund target depends on your income, household expenses, job stability, and personal circumstances.
Consider Debt Consolidation Carefully
Debt consolidation combines multiple debts into a single loan or payment arrangement.It can simplify repayment when you are managing several balances, but consolidation is not automatically cheaper.
Before choosing a consolidation option, compare:
- Interest rate
- Total repayment cost
- Loan duration
- Processing or origination fees
- Prepayment conditions
- Monthly payment
- Whether the new payment fits your budget
A lower monthly payment can look attractive while still costing more overall if the repayment period becomes much longer.
Talk to Creditors if You Are Struggling
If debt payments have become difficult to manage, contacting your lender early may be better than ignoring the problem.
Debt Management Depending on the lender and type of debt, options may include revised payment arrangements, hardship programs, or other assistance.
Keep records of conversations and carefully review any revised terms before agreeing to them.
If your situation is complicated, consider speaking with a qualified financial counselor or other appropriate professional.
Be Careful With Debt Relief Offers
Debt problems can make people vulnerable to unrealistic promises.
Be cautious about companies or individuals promising to eliminate debt quickly, guarantee specific results, or asking for large upfront fees without clearly explaining the service.
Before working with a debt-relief provider, research the organization, understand its fees, read the agreement carefully, and make sure you understand what could happen to your credit and accounts.
If an offer sounds too easy, take time to investigate it.
Use Automation to Stay Organized
A Debt Management missed payment can create unnecessary stress and may result in fees or other consequences.
Automatic payments can help you stay on schedule for bills and loans, provided you have enough money in the linked account.
You can also use calendar reminders for:
- Credit card due dates
- Loan payments
- Subscription renewals
- Insurance premiums
- Annual financial reviews
Automation is particularly useful when you have several financial commitments.
Track Your Progress Every Month
Debt management becomes easier when you can actually see your progress.
At the end of each month, record:
- Total debt balance
- Amount paid
- Interest charged
- Additional payments
- Savings balance
- New borrowing, if any
For example:
| Month | Starting Debt | Payments | Ending Debt |
|---|---|---|---|
| January | ₹2,00,000 | ₹15,000 | ₹1,85,000 |
| February | ₹1,85,000 | ₹17,000 | ₹1,68,000 |
| March | ₹1,68,000 | ₹18,000 | ₹1,50,000 |
Your actual results will depend on interest, fees, and the terms of your debts, but tracking the balance can make progress easier to understand.
Common Debt Management Mistakes
Even a well-intentioned Debt Management repayment plan can go off track.
Some common mistakes include:
Ignoring Interest Rates
Two debts with the same balance can cost very different amounts when their interest rates differ.
Paying Extra Without Checking Loan Terms
Some loans have specific prepayment conditions. Check your agreement before making large additional payments.
Closing Every Credit Account Immediately
Closing accounts may have implications for your credit profile depending on your circumstances. Consider the broader effect before making changes.
Having No Emergency Savings
Putting every available rupee toward debt can leave you vulnerable when an unexpected bill arrives.
Taking New Loans to Cover Old Spending
Borrowing repeatedly without addressing the underlying budget problem can create a cycle of debt.
Following a Budget That Is Too Strict
A budget needs to be realistic enough to maintain over time.
A Simple Debt Management Plan
Debt Management If you are not sure where to begin, start with these steps:
1: List every debt.
2: Record each balance, interest rate, minimum payment and due date.
3: Create a monthly budget.
4: Make all required payments on time.
5: Choose either a snowball or avalanche strategy.
6: Direct available extra money toward your chosen priority debt.
7: Avoid unnecessary new borrowing.
8: Keep some emergency savings.
9: Review your progress every month.
10: Adjust the plan when your income, expenses or debt situation changes.
Debt Management and Saving Money Can Work Together
It can feel like you have to choose between paying Debt Management and saving money, but your financial plan can include both.
For example, you might:
- Make all required debt payments.
- Build a small emergency cushion.
- Direct additional money toward expensive debt.
- Reduce unnecessary expenses.
- Increase savings as debt decreases.
- Redirect former debt payments toward long-term financial goals once balances are under control.
The balance will look different for every household.
FAQ’S
1. What is debt management?
Debt management is the process of organizing, repaying, and controlling debt while creating a realistic plan for your overall finances.
2. What is the best way to start managing debt?
Start by listing every debt, including the outstanding balance, interest rate, minimum payment, and due date. Then create a monthly budget and choose a repayment strategy.
3. What is the debt snowball method?
The debt snowball method focuses on paying off your smallest debt first while making required payments on your other debts.
4. What is the debt avalanche method?
The debt avalanche method prioritizes the debt with the highest interest rate. This can help reduce the amount of interest paid over time.
5. Should I pay off debt or save money first?
A balanced approach can be useful. Continue making required debt payments while maintaining an emergency cushion, then direct additional money toward high-cost debt when appropriate.